Please read this first
Talk with Nina before you register for the NACA Homebuyer Workshop.
There is a short form Nina needs to complete with you before the workshop so NACA connects you back to her when you are qualified and ready to search for a home. It takes only a few minutes, it costs you nothing extra, and doing it in the right order protects your path. If you have already attended a workshop, tell Nina right away so she can guide your next step.
Free NACA Guide
Buying a Home Through NACA, Explained Simply
NACA can be one of the most affordable ways to buy a home in America — no down payment, no closing costs, and no mortgage insurance. In return, NACA asks you to follow its process, in its order, with patience and discipline. This guide shows you what that means before you start.
- No down payment, no closing costs, no mortgage insurance
- No credit score consideration — your payment history and budget decide
- All 10 steps, in order — home search comes only after you are NACA Qualified
- The cash you still need, and how payment shock works
- Why you talk with Nina before the workshop — not after
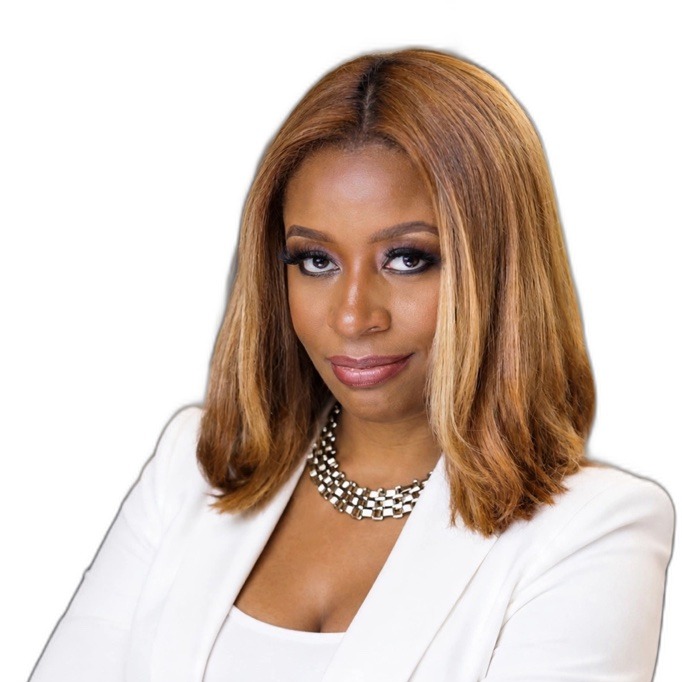
Nina GuytonAssociate Broker, eXp Realty · Registered NACA Outside Agent
What NACA is — and what it is not
A nonprofit, not a bank
NACA stands for the Neighborhood Assistance Corporation of America. It is a nonprofit housing counseling organization, not a bank and not a government loan program like FHA or VA. NACA counselors help you get ready, review your full household budget and payment history, and qualify you in NACA’s own way. A participating lender then funds the mortgage.
NACA does not qualify you by credit score. It looks at your actual record — whether you have paid rent and other bills on time for the past 12 months, whether your income is stable and documented, and whether the new payment truly fits your budget. That is character-based lending: your history and your budget do the talking.
The process
The 10 steps, in order
You do not move to the next step until NACA moves you. Steps 1 through 3 come before any home search.
Homebuyer Workshop
A free workshop, about 4 hours, required for everyone. Afterward you register in the NACA Member Portal, submit documents, and sign the membership forms. Talk with Nina before you register — workshop registration: nacalynx.com.
Counseling and preparation
You meet with a NACA counselor who reviews your income, budget, debts, and payment history. If something needs work, you receive an Action Plan and keep meeting until it is complete.
NACA Qualified
This is NACA’s pre-approval. It is detailed, and it is the milestone everything else depends on.
Home search
Only now do we search. You attend a Purchase Workshop, receive your Qualification Form showing your maximum payment and price, and we look for homes inside those numbers.
Purchase contract
Nina confirms the home fits your qualification with your counselor before we write, and the contract includes the protections NACA requires.
Inspection and property review
A NACA-approved home and pest inspection is required and cannot be waived. NACA reviews any health, safety, or structural repairs the home needs.
Bank application
Your counselor re-checks that your income, savings, debts, and on-time payments have stayed on track, then submits your bank application.
Processing and underwriting
Insurance, any repair bids, and final walk-through happen here.
Closing
Closing takes place at a NACA office with an approved settlement agent. You bring funds only for prepaids and reserves, not closing costs.
Support after purchase
Your membership continues, and help is available if your circumstances change.
Timing varies by buyer. A buyer who is document-ready with 12 clean months of payments may qualify in weeks. A buyer who needs to build savings or address late payments may need several months. Once under contract, NACA aims to close in about 35 days when no major repairs are needed, and 45 to 60 days when they are.
The money part
No down payment does not mean no cash
Plan to have savings for these items, even with NACA:
- Earnest money — a deposit that shows the seller you are serious; it is returned at closing.
- Home inspection — required, and paid by you.
- Prepaid taxes and insurance — amounts collected at closing to start your escrow account.
- Reserves — savings NACA requires you to still have after closing.
Payment shock, explained
If your rent is $1,200 and your new mortgage payment would be $1,800, the $600 difference is your payment shock. NACA will ask you to save that $600 every month, consistently, and show it in your bank statements. That saving pattern is how you prove the new payment fits your life — start it as early as you can.
Staying on track
Rules that keep you qualified
Qualification is not a one-time pass. From your first counseling appointment until closing day, NACA expects you to:
- Pay every bill on time, every month — especially rent.
- Keep canceled checks or bank records that prove your rent payments.
- Take on no new debt. No new car, furniture loan, or credit card balance without talking to your counselor first — new debt can undo your qualification.
- Keep your income stable and keep saving your payment shock amount.
- Keep submitting fresh pay stubs, bank statements, and rent proof when NACA asks — even after you are qualified.
- Complete NACA’s participation activities each year, including at least one before qualification and one before closing, and keep your household membership current.
Common questions
Questions buyers ask most
Can I look at homes now and do NACA later?
No. With NACA, qualification comes first. Looking first usually leads to disappointment, because a home you love may not fit your qualified payment — and a contract written the wrong way will not be accepted.
My credit score is low. Am I out?
Not because of the score alone. What matters is your last 12 months of on-time payments, your documented income, your budget, and your savings pattern. If those need work, your Action Plan tells you exactly what to fix.
How long will this take?
It depends on how ready you are when you start. Buyers who begin document-ready move fastest. Either way, this is a process measured in weeks to months, not days — and the buyers who succeed are the ones who stay consistent the whole way through.
Be ready
What to gather before counseling starts
Having these ready makes your first counseling appointments move faster:
- Photo ID and Social Security cards for everyone who will be on the mortgage
- Recent pay stubs, and documentation for any other household income
- Recent bank statements for all accounts
- Proof of rent payments for the past 12 months — canceled checks or bank records
- Recent tax returns and W-2 forms, if you have them
- A simple list of your monthly debts and bills, so we can build your real budget together
Do not worry if something is missing. Bring what you have, and your counselor’s Action Plan will tell you exactly what is still needed.
NACA program terms, rates, income limits, and loan limits change and are confirmed by NACA for each member. This guide is an educational summary prepared by Nina Guyton, eXp Realty, LLC, and is not a loan offer, pre-approval, or guarantee of qualification. Prices and incentives are subject to change without notice; please verify with Nina Guyton, eXp Realty, LLC.